💰 Home Value 101What's Your Home Worth? Understanding Your Property's ValueYour home's value isn't just one number, it's shaped by several factors working together. Here's what actually moves the
Dated: July 24 2026
Views: 66
Paying PMI every month? Thanks to rising home values in West Michigan, you may be able to drop it, without writing a big check. Here's how.
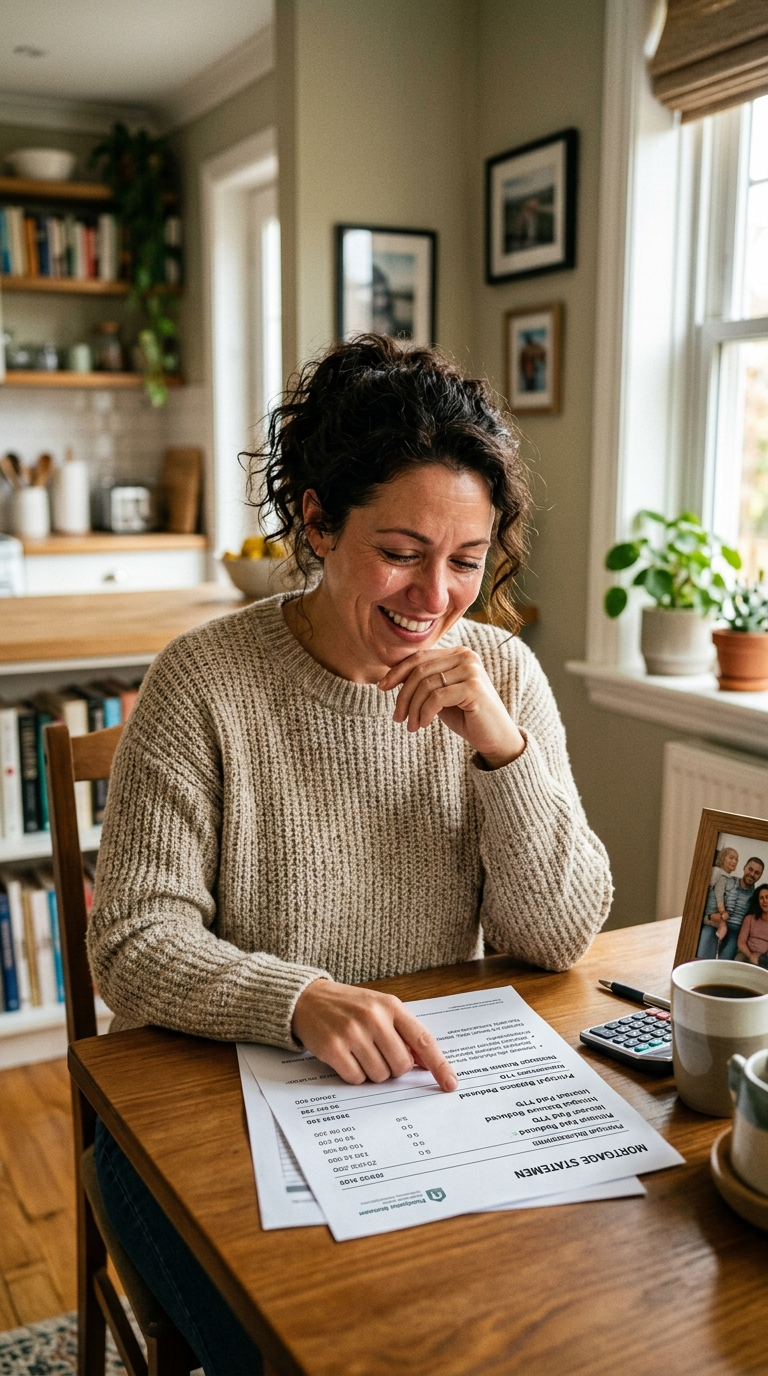
If you bought your home with less than 20% down, you're probably paying private mortgage insurance (PMI) — an extra monthly cost that protects your lender, not you. The great news? It doesn't have to last forever.
And here's the part many homeowners miss: with how much West Michigan home values have climbed, you may already have enough equity to remove PMI, without putting a single extra dollar down. Let me walk you through how it works, in plain English.
PMI is tied to your loan-to-value ratio (LTV) — basically, how much you owe compared to what your home is worth. Two key numbers to remember:
The magic here is that "value" can rise — so appreciation can push you across that line faster than your payments alone.
This is the strategy that surprises people. If your home is worth more than when you bought it (very common in West Michigan lately), your equity has grown even if your loan balance has barely moved. Here's how to use it:
Compare what you owe to what similar homes nearby are selling for now. I'm happy to run a free comparison of recent local sales so you know roughly where you stand.
Ask about their specific rules for removing PMI based on current value. This step matters, many lenders require a "seasoning" period (often about two years of ownership) and may ask for a lower LTV (sometimes 75%) when you're relying on appreciation rather than payments.
If your numbers look promising, the servicer will typically want a professional appraisal or valuation to confirm the new value. This usually runs about $300–$600, far less than years of PMI payments.
If the appraisal confirms you're at or below their threshold, and you have a clean recent payment history with no second liens, submit your written cancellation request. Goodbye, PMI!
Curious how much your West Michigan home is worth today? I'll run a free local comparison so you know where you stand.
Call or Text: (269) 217-8303Dropping PMI can save you hundreds a month, real money back in your pocket. I'm always happy to help you understand your home's current value and point you to a trusted lender to handle the paperwork.
Removing PMI is one of those quiet wins that can meaningfully lower your monthly payment without a big outlay. If you've owned your West Michigan home for a while, it's absolutely worth a look. Let's find out where you stand. 💛
A quick note: PMI removal rules vary by lender, loan type, and investor guidelines, and the thresholds here reflect general 2026 standards. This is general information, not financial or legal advice. Always confirm your servicer's exact requirements, and I'll happily connect you with a trusted local lender.
Questions about PMI or your equity? Call or text me at 📲 (269) 217-8303.
Say Hi to Rachel
Leaning on my previous career as an Interior Designer, I am able to envision the function and potential of homes that will fit each of your unique needs. I am originally from a small, farm town ....
💰 Home Value 101What's Your Home Worth? Understanding Your Property's ValueYour home's value isn't just one number, it's shaped by several factors working together. Here's what actually moves the
❄️ Seasonal PrepWinter Prep, Spring PayoffA little home maintenance this winter can mean a smoother, stronger sale come spring. Here's what to tackle now if listing is on your radar for next
📊 Market UpdateMortgage Rates Just Hit a 20-Month High, Here's What It Actually Means for YouRates moved the opposite direction many expected this month. Here's the real data, and what smart
📋 Closing Day GuidePreparing for Closing Day: The Ultimate Guide for Home SellersYou've accepted an offer, congratulations! Here's exactly what to handle between now and the closing table so the
 Listing information is provided by Participants of the MichRIC MLS. IDX information is provided exclusively for personal, non-commercial use, and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information deemed reliable but not guaranteed. ©: MichRIC MLS. Last Update September 26, 2026 10:13 PM UTC
